Moving to Spain with stock options? Discover why grant, vesting, exercise and a later share sale require separate tax analysis under the Beckham Law.
Read more ›
Receiving carried interest after moving to Spain? We examine a Spanish tax ruling and the factors that can affect your individual position under the Beckham Law.
Read more ›
A share sale and the end of your role in the group can have different consequences. We review your exit and Spanish tax position together.
Read more ›
A holding company shareholder and director may qualify for Spain’s Beckham regime. Review the risks and coordinate your move with your business structure.
Read more ›
DGT ruling V2199-25 excludes the home energy efficiency tax credit from the Beckham regime. Review the limits, other deductions and the risks of opting out.
Read more ›
Spanish rental income under the Beckham Law: gross rent, expenses, residential letting relief, empty days and your Form 151 review.
Read more ›
Has your employer changed payroll withholding to 47%? We explain the 24% rate, the €600,000 threshold, ruling V1971-25 and how to review errors before Form 151.
Read more ›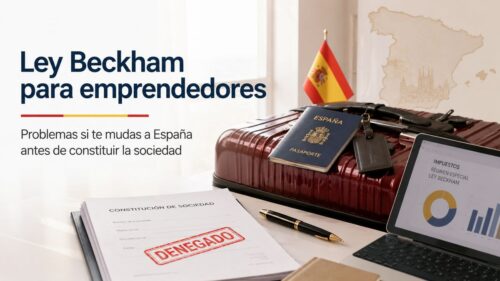
Moving to Spain before forming a company can raise questions about the reason for the move. We explain the evidence, Form 149 and how to review an AEAT refusal.
Read more ›
Can a remote employee use the Beckham Law without a digital nomad visa? We explain ruling V2460-25, the tax requirements and the evidence needed for Form 149.
Read more ›
Filed Form 100 instead of Form 151 under the Beckham Law? We explain ruling V1921-25, the correction process and what to check before responding to the AEAT.
Read more ›